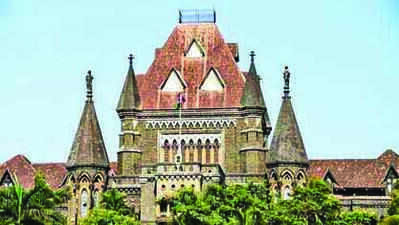
Mumbai: The licensing of copyright in a film by its producer and original copyright holder, is not information technology software under the Goods and Services Tax (GST) Act whether delivered via a digital link or hard disk, the Bombay High Court held and set aside a nearly Rs 80 crore demand plus interest and penalty imposed on producer Karan Johar’s two production companies.The films were ‘goods’ attracting lesser GST than an IT software, the producer had argued. Equating “digital content” with “software”, the core error underlying the impugned orders, has no statutory basis, held Justices M S Karnik and Sandesh Patil in a September 10 judgement made available last week.In a few cases, Dharma Productions, which last year petitioned the HC to challenge the demand, said it had transferred the cinematographic films electronically, while some were sent as hard discs. No software was supplied to the distributor in the course of such transfer, argued senior counsel Darius Shroff for Dharma Productions.“Whether content is transmitted physically (encrypted hard disks) or electronically, the mode of delivery cannot determine classification, which must turn on the essential character of the supply,’’ the HC ruled, after hearing additional govt pleader Jyoti Chavan for the State and Goods and Services Tax (GST) department and its deputy commissioner whose four orders passed in 2021 were under challenge and set aside.“The dominant nature and essential character of the supply, not its mode of transmission, must govern classification,’’’ the HC ruled, saying “classification of theatrical rights cannot change when the distributor licenses the exhibitor”.There is no difference between a license given by the license holder to the distributor, and a license given by the distributor to the exhibitor. The distinction sought to be raised by the adjudicating authority is therefore flawed, the HC stressed coming to the producer’s rescue.